Looking after your best interests so you can focus on building your nest.

LET'S TALK
Let us help you find a mortgage that is best suited to your needs. 
We specialize in educating clients to ensure stress-free mortgage financing. It would be a pleasure to work with you.

Mortgage financing can be confusing, it doesn't have to be, here's the plan.

Get started right away

The best place to start is to connect with us directly. The mortgage process is personal. Our commitment is to listen to all your needs, assess your financial situation, and provide you with a clear plan forward.

Get a clear plan

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let us cut through the noise, we'll outline the best mortgage products available, with your needs in mind.

Let us handle the details

When it comes time to arranging your mortgage, we have the experience to bring it together. We'll make sure you know exactly where you stand at all times. No surprises. We've got you covered.
Cell: 604-805-1833

Office: 604-943-8943

Mortgage Expert, AMP

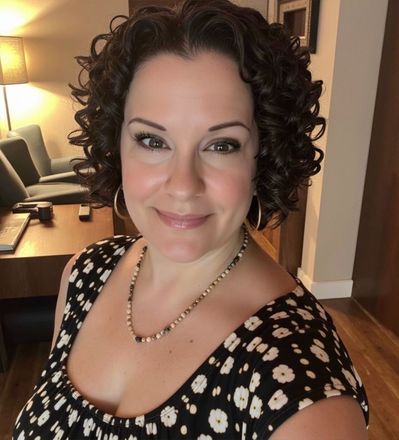
I have been in the mortgage industry for almost 27 years. My first 16 years were spent working for a large Canadian chartered bank. During that time I helped develop credit products, managed branches and ran sales teams. While the management experience has been valuable, it was working one on one with clients that I truly enjoyed.


After the birth of my son in 2003, I left my beloved banking career and took on the challenge of an independent mortgage broker. From that point on, I never looked back. Since then I have assisted my clients in finding the perfect mortgage for them.


Any one of my clients will tell you I bring an energy and enthusiasm to the process of buying, refinancing or renewing your home. I love what I do and I have fun doing it. I am proud to say that I have generations of families that I have put into the biggest purchase of their lives, and while that might make me feel a little old, those types of incredible relationships are what make me the most proud of what I do.


My clients know that I am always here to assist. If you’re looking for a mortgage, a second opinion or just need to ask a couple of questions, give me a call. I would LOVE to hear from you!


Meet Shari - my director of client care.

Here are some nice things clients have said about working with us.

Articles to keep you learning
By Lisa Manwaring • November 4, 2026
Can’t Find the Right Home After You’re Pre-Approved? There’s Another Option The best place to start any home purchase is with a mortgage pre-approval. It gives you clarity around your budget and lets you shop with confidence. But what happens when you’ve been pre-approved, you know where you want to live—and nothing suitable fits your price range? This is a common challenge, especially for first-time homebuyers. Before buyer fatigue sets in, it may be worth considering a different approach: buying a home that needs work and financing the renovations as part of your mortgage . What Is a Purchase Plus Improvements Mortgage? A purchase plus improvements program allows you to buy a property and include the cost of approved renovations directly in your mortgage. This can be a great solution if: You can’t find a move-in-ready home within budget You’re open to renovations You want to customize the home from the start It opens up more options and can help you get into a location or property that would otherwise be out of reach. How the Process Works While the idea is straightforward, the process itself is structured and requires planning. Here’s a high-level overview: Renovation quotes are required upfront You’ll need detailed quotes for the work you want completed before final mortgage approval. Renovations must add value The lender must be satisfied that the improvements will increase the property’s value accordingly. Funds are reimbursed, not advanced You pay for the renovations initially. Once the work is completed and verified by an appraiser, the lender reimburses you and adds the cost to your mortgage. With the right guidance, this process is very manageable—but it’s important to understand the steps before committing. Is This Program Right for You? Purchase plus improvements isn’t for everyone. Buying a home is already a big undertaking, and adding renovations can increase stress—especially if timelines, budgets, or contractors become challenging. That said, if you’re financially prepared and like the idea of shaping the home to fit your needs, this program can be an excellent way to get more value and flexibility from your purchase. Final Thoughts If you’re struggling to find the right home after being pre-approved, you may not need to lower your expectations—you may just need a different strategy. If you’d like to explore whether a purchase plus improvements mortgage makes sense for you, feel free to connect. I’d be happy to walk you through the process and outline exactly what this option would look like in your situation.
By Lisa Manwaring • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Lisa Manwaring • October 21, 2026
Missed a Credit Card or Line of Credit Payment? Here’s What to Do If you’ve missed a payment on a credit card or line of credit and you’re worried about how it might affect your credit—or your future mortgage—this is for you. First things first: 👉 If you currently have an overdue balance, log in and make the minimum payment now. Seriously. Do that first. Everything else can wait. If You’re Only a Few Days Late Here’s the good news: Credit bureaus don’t record late payments until they reach 30 days past due. So if you missed a due date by a few days and paid it as soon as you noticed, it typically won’t show up on your credit report as a late payment—as long as you’re under the 30-day mark. That said, it never hurts to double-check. You can call your credit card company, explain what happened, and confirm the account is back in good standing. If you normally pay on time, they may even reverse the interest charged. It doesn’t hurt to ask. If You’re 30, 60, or 90 Days Behind If payments have gone past 30 days, your credit has likely been impacted—but the situation is still fixable. The most important step is to: Bring all accounts current as soon as possible Make at least the minimum payment on every account The faster you catch up, the more you limit the damage. Ignoring missed payments only makes things worse. If Cash Flow Is Tight If you’re struggling to make payments, communication matters. Contact your lender and keep them informed—even if you can’t pay right away. Lenders are far more willing to work with you when you’re transparent. What hurts your credit most is silence . If lenders don’t hear from you after repeated missed payments, they may write the balance off as bad debt and send it to collections. Collections can significantly impact your credit and stay on your report for years. How This Affects Mortgage Qualification Repeated missed payments can make qualifying for a mortgage more difficult—but timing matters. Once you’re back to making regular, on-time payments: Your credit can improve over time The impact of past mistakes becomes less significant If you’re planning to buy a home in the next couple of years, addressing credit issues early gives you far more options later. Final Thoughts Missing a payment doesn’t mean you’re “bad with money,” and it doesn’t mean homeownership is off the table. What matters most is how quickly you respond and how consistent you are going forward . If you’d like help reviewing your credit report or understanding where you stand from a mortgage perspective, feel free to connect. I’d be happy to walk through it with you and help you create a clear path forward.